Back to News
News AlertWorld Money
The $617 Billion Shift: Why B2B Platforms Are Embedding the Bank
T
Author
Tushar Shrivas
Published
September 28, 2026
Reading Time
5 MIN READ
Spread the Word
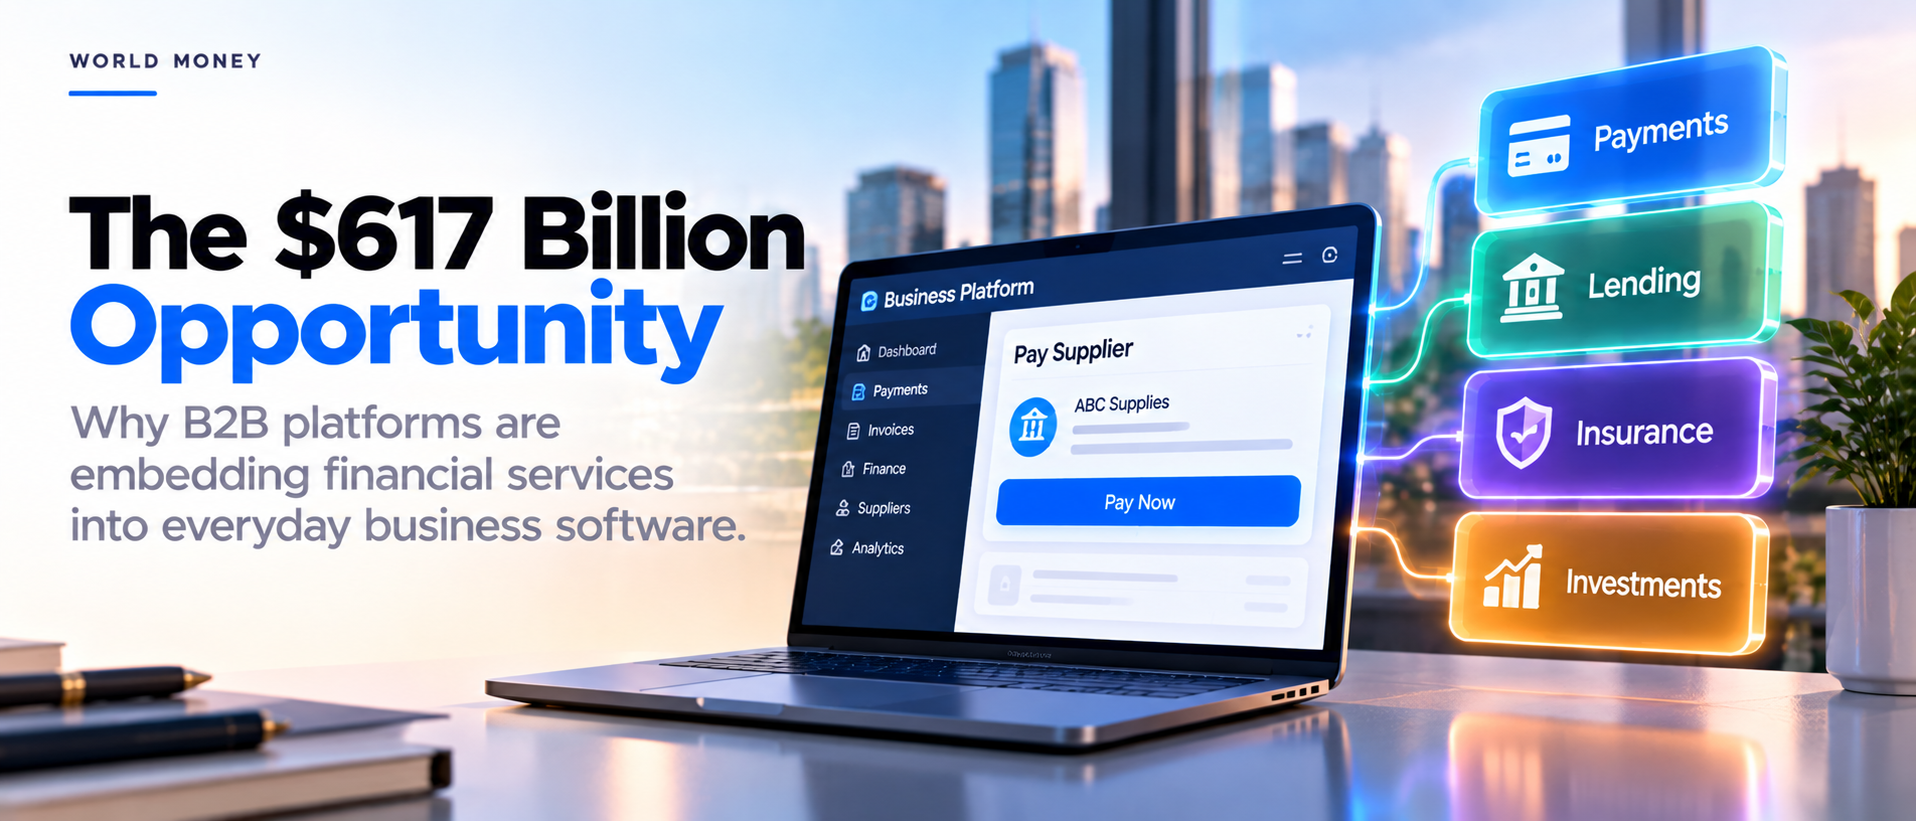
Embedded finance could reach $617 billion by 2031 as B2B growth accelerates. Here's why financial services are moving inside everyday business software.
$617 billion embedded finance, embedded finance 2031, B2B embedded finance, embedded banking, embedded payments, fintech APIs, digital banking, B2B payments
The $617 Billion Shift: Why B2B Platforms Are Embedding the Bank
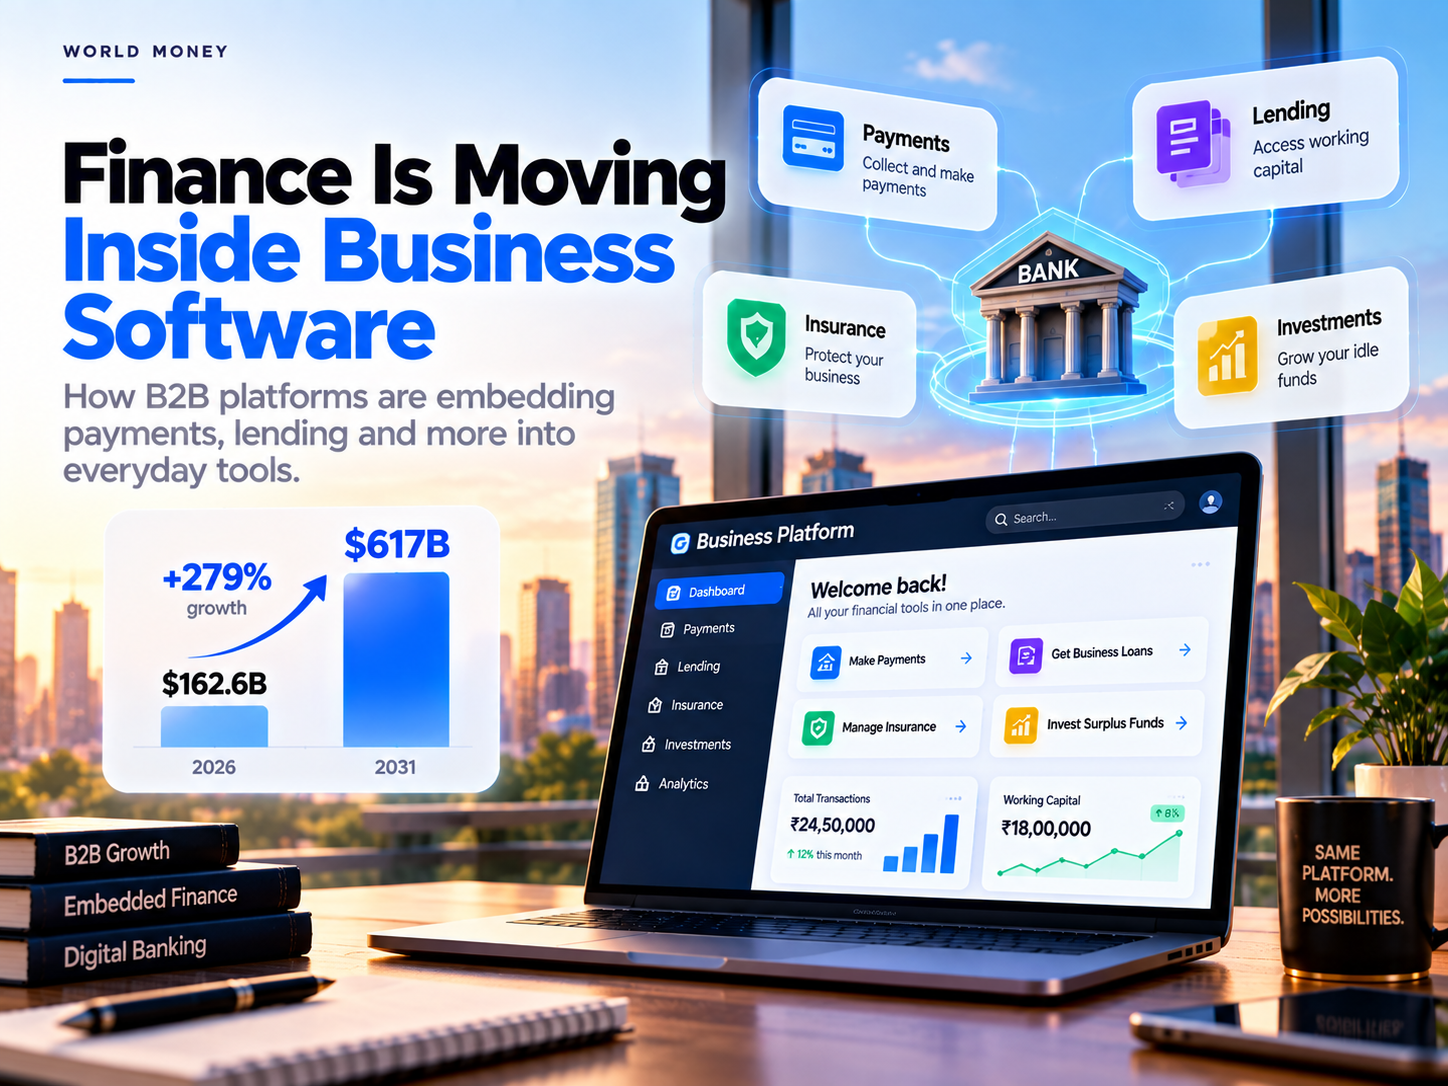
Corporate finance is increasingly moving away from standalone banking portals and into the software businesses already use every day. A new Juniper Research forecast puts global embedded-finance revenue at $617 billion by 2031, up from $162.6 billion in 2026 — a 279% increase. The research identifies B2B as the fastest-growing segment, with B2B embedded finance forecast to increase by 390% over the next five years. Juniper Research
Banking Is Moving Inside Business Software
Embedded finance means financial services are built directly into non-financial platforms through APIs and white-label infrastructure. Instead of sending users to a separate bank or financial application, a business platform can integrate payments, lending, banking, insurance or investment services into its own workflow. This makes finance increasingly invisible to the end user while remaining an important part of the software experience. GlobeNewswire
The B2B opportunity is particularly significant because business transactions are often more complicated than ordinary consumer payments. Companies need to handle supplier payments, employee expenses, receivables, working capital and cross-border transactions. Embedding these capabilities directly into business software can reduce the need to switch between multiple systems and can make financial operations part of the normal workflow rather than a separate activity. Juniper's latest research specifically identifies the rapid digitisation of B2B payments as a major opportunity.
Why APIs Are Changing Corporate Finance
The technology behind this shift is largely API-driven infrastructure. Financial providers can expose capabilities that software platforms can integrate into their own products, allowing businesses to offer financial functions without building an entire banking system themselves. The result can be a branded financial experience where the customer interacts primarily with the business platform rather than the underlying financial provider. GlobeNewswire
Payments and lending are already among the biggest embedded-finance opportunities. Previous Juniper research cited by Visa found that embedded payments and embedded lending represented the majority of global embedded-finance revenue, highlighting how financial infrastructure can become deeply connected to the commercial software businesses already depend on. Visa
B2B Could Become the Bigger Story
Consumer-facing embedded finance has received much of the attention because shoppers can make payments or access financial services without leaving an app. But the B2B market could have a much larger operational impact. A marketplace, accounting platform or business-management system could potentially integrate payment acceptance, financing and other financial services into the same environment where companies already manage their operations.
The latest Juniper forecast suggests this isn't simply a theoretical opportunity. B2B is projected to be the fastest-growing embedded-finance segment through 2031, expanding 390% over five years. That growth reflects the broader digitisation of business payments and the increasing demand for financial services that can be delivered directly through digital platforms. Business Insider
The Bank Doesn't Disappear — It Moves Behind the Screen
Calling this the "replacement of banks" would be misleading. Banks and regulated financial institutions remain critical because they provide much of the underlying financial infrastructure, regulatory compliance and balance-sheet capacity. What is changing is where customers encounter financial services. The financial product may increasingly appear inside accounting software, marketplaces, commerce platforms or other business applications instead of a traditional banking interface.
Juniper's latest research also highlights vertical specialisation as an important competitive factor, with Stripe, Adyen, Plaid, Marqeta and SoFi identified among its leading embedded-finance vendors. The implication is that success may depend less on simply offering financial APIs and more on tailoring them to specific industries and business workflows. Juniper Research
What It Means for World Money
The biggest change may be difficult for consumers to see. A company receiving an invoice, paying a supplier or accessing working capital may eventually complete those financial actions without opening a traditional banking portal at all. The banking infrastructure remains underneath the transaction, but the visible interface becomes the software where the business already works.
The global market forecast is therefore more than another fintech growth number. The projected $617 billion represents a broader shift in how financial services are distributed: banking capabilities are becoming components that can be embedded into digital platforms rather than destinations customers must visit separately.
The real question is no longer whether finance can be embedded into software. That is already happening. The bigger question is how much of the global financial system will eventually operate behind the scenes of the platforms businesses and consumers already use. If Juniper's forecast is right, B2B could be one of the biggest forces accelerating that transition over the next five years.
FAQ
What is embedded finance?
Embedded finance is the integration of financial services such as payments, lending, banking, insurance and investment directly into non-financial platforms using technologies such as APIs and white-label infrastructure.
How big could the embedded-finance market become?
Juniper Research forecasts global embedded-finance revenue will reach $617 billion by 2031, compared with $162.6 billion in 2026 — representing 279% growth.
Why is B2B embedded finance growing so quickly?
Juniper identifies B2B as the fastest-growing segment, forecasting 390% growth over five years, driven in part by the digitisation of B2B payments.
Does embedded finance mean traditional banks will disappear?
No. Embedded finance changes how financial services are delivered, not necessarily who provides them. Banks and other regulated financial institutions can continue providing the underlying financial infrastructure while customers interact with services through other platforms.
Which financial services are being embedded?
Payments and lending are major embedded-finance categories, while insurance and investment services are also increasingly being integrated into digital platforms.
Tushar Shrivas
B.Tech CS@ Shri Balaji Institute of Technology & Management
I write at Metaplugs — breaking down the latest in tech, economics, and business into simple, impactful stories for everyday readers. Passionate about software testing and global finance.